MULTI-PARTNER FIRM CPA SERVICES

Accounting, Tax & CFO Services for Multi-Partner Firms

From partner compensation to profit allocation and K-1s, we bring clarity and fairness to partnership finances.

Serving Seattle-area multi-partner firms since 1971 · Licensed WA CPAs

Accounting Built Around How Multi-Partner Firms Operate

Greenwood Ohlund provides multi-partner firm accounting for law partnerships, medical and dental groups, consulting firms, and AEC partnerships across the Seattle area. Whatever compensation model your firm uses, formula, lockstep, or something purpose-built, we maintain the documentation behind it. Partner draws, distributions, and capital balances all move during the year, and tracking them against the agreement as they go is what keeps year-end a mere reporting task instead of a negotiation. When a partner retires or a new one buys in, the records that determine the price are already there.

We handle partner compensation accounting, capital account maintenance, and the partnership tax work underneath it, so what each partner is owed and what each partner owes are both documented and defensible.

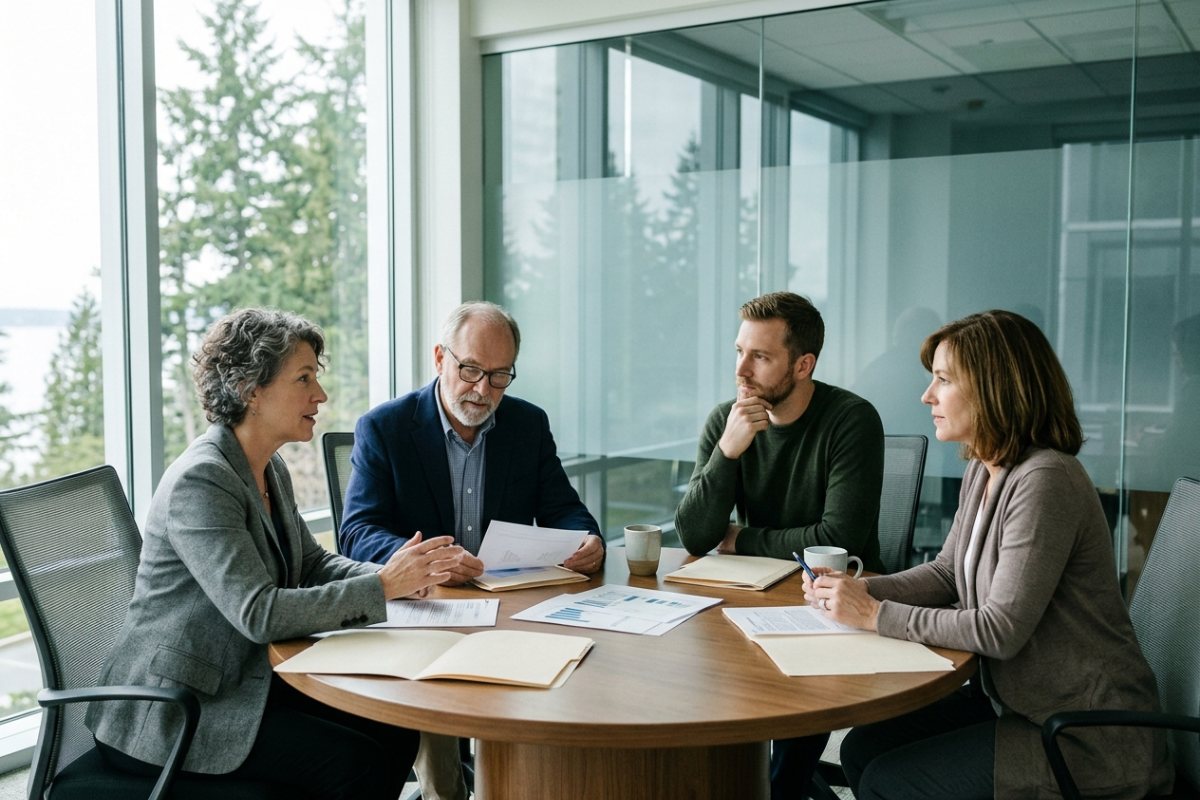
Partners of a professional services firm reviewing financial reports around a conference table

OUR CLIENTS

The Challenges Multi-Partner Firms Face and How We Help

We model what each structure pays out, partner by partner, before the vote. Every partner sees their own number before the vote.

We allocate according to your operating agreement rather than a pro-rata default, and maintain the capital accounts that support it under §704(b).

The numbers that price it are already current, because we’ve been tracking basis and capital balances all along. We handle the §736 payments to a departing partner and the allocation adjustments for everyone who stays.

We prepare the partnership return and the K-1s together, time them so partners can meet their own estimates, and run the PTET election decision as part of planning.

What Makes Multi-Partner Firms Accounting Different

Partnership tax follows the operating agreement, not the ownership split. Special allocations only hold up if capital accounts are maintained under §704(b), and guaranteed payments under §707(c) are taxed differently from a distributive share, which changes what a partner owes and when. Both are decided by how the agreement is written and how the books are kept against it.

Transitions carry their own mechanics. A departing partner’s payments split between §736(a) and §736(b) with different tax treatment on each side, and a §754 election lets the firm adjust the basis of its assets for an incoming partner under §743(b), which is valuable and easy to miss at the moment it has to be made. Washington adds a layer on top: the PTET election shifts state tax to the entity, and B&O tax applies at the entity level on gross receipts.

Partnership agreement and capital account summaries under review at a conference table

We serve firms like yours

Firms Like Yours

We work with a wide range of multi-partner firms, including:

Why Multi-Partner Firms Choose Greenwood Ohlund

Decades serving professional service firms

We’ve been doing this since 1971.

Tax, audit, accounting, and CFO expertise, one firm

Most firms our size don’t offer all four under one roof. You get a tax team, an audit team, and a CFO-level advisory team who already talk to each other, instead of coordinating three separate vendors yourself.

Seattle-rooted, with clients across Washington and beyond

We’re based in Seattle and built around the Pacific Northwest, with clients in other states when the relationship calls for it.

A relationship that runs all year, not just tax season

We’re recognized as a Peak Firm and a PSBJ Washington’s Best Workplaces honoree, and that same culture shows up in how we work with clients: regular conversations and actual availability, not a firm you hear from once a year.

Your Multi-Partner Firms Team

RECENT NEWS

Latest Updates and Insights from Greenwood Ohlund

QuickBooks Online vs. Sage Intacct vs. Business Central – Accounting Software Comparison

QuickBooks Online vs. Sage Intacct vs. Business Central: Which Accounting Software Is Best for Your Business?

What is the best accounting software for a small or midsized business or nonprofit organization? For many organizations, QuickBooks Online (QBO) is our preferred accounting platform because of its ease of use, widespread familiarity among accounting professionals, relatively low cost, and ability to support efficient financial reporting. However, Sage Intacct and Microsoft Dynamics 365 Business Central offer more sophisticated capabilities
Read More »
Woman comparing CRUT and NIMCRUT documents while reviewing financial planning options.

CRUT vs. NIMCRUT: Why the Tax and Distribution Rules Matter

Understanding how charitable remainder trusts affect your cash flow, income taxes, and long-term financial planning. Key takeaway: Choosing between a standard charitable remainder unitrust (CRUT) and a net income with makeup charitable remainder unitrust (NIMCRUT) can affect how much income you receive, when you receive it, and how your distributions are taxed. If you own highly appreciated assets, a charitable

Read More »
Accounting professionals using AI-assisted financial dashboards to analyze business performance

How Outsourced Accounting and AI Can Help Your Business Flourish 

A practical look at how AI can make outsourced accounting faster, more insightful, and more valuable to management  Artificial intelligence is changing the accounting profession, but the biggest opportunity is not simply automating bookkeeping.  The greater opportunity is combining AI with outsourced accounting professionals to produce faster financial information, stronger analysis, better documentation, and more useful insight for management.  For

Read More »
Recent News

Latest Updates and Insights from Greenwood Ohlund

University Child Development School

Client Spotlight Q&A: University Child Development School

When did GO start working with UCDS, and how has this partnership evolved over the years?
 GO has proudly partnered with UCDS since 2022 to support the school’s financial stewardship and long-term sustainability. Over time, that partnership has evolved alongside the school’s growth and continued focus on innovative education, strong governance, and mission-driven planning. In what ways does the GO

Read More »
Ballard Food Bank

Client Spotlight Q&A: Ballard Food Bank

Ballard Food Bank When did GO start working with Ballard Food Bank, and how has this partnership evolved over the years? GO has proudly partnered with Ballard Food Bank since 2010, beginning with onsite monthly accounting support. In 2020, our relationship evolved to providing their annual audit and Form 990 preparation. In what ways does the GO Team support the

Read More »
FAQ

Multi-Partner Firms Accounting FAQs

There’s no single right model. Formula pays on measurable contribution, lockstep pays on seniority, and most firms land somewhere between. What matters more than the model is whether every partner can see how their number was reached. We model the options against your current payouts before you commit.

Profit follows the operating agreement, not ownership percentages. If the agreement calls for special allocations, the IRS respects them only when capital accounts are maintained under §704(b). We allocate to the agreement and keep the accounts that support it.

A capital account tracks what each partner has put in, been allocated, and taken out. Draws reduce it during the year. When the two aren’t tracked against each other as they go, year-end becomes a reconstruction. We maintain both on a monthly close.

A departing partner’s payments split between §736(a) and §736(b), which are taxed differently. For an incoming partner, a §754 election lets the firm adjust the basis of its assets under §743(b). Both decisions have timing attached, so they belong in planning rather than at filing.

The pass-through entity tax election shifts state income tax from the partners to the firm, which can preserve a federal deduction the partners would otherwise lose. Whether it helps depends on where your partners live and file. As a professional partnership CPA in Seattle, we run that math for Washington firms with partners in multiple states.

It depends on the number of partners, how complex your compensation model is, and how clean the existing books are. We start with a conversation about your firm, then build a proposal around it.

CONTACT US

Let’s Bring Clarity to Your Partnership’s Finances

Partner compensation, profit allocation, or K-1s and PTET: we can take it from here. Reach out and we’ll start with a conversation about your firm.